NMPA - Automatic ringfencing of cash transfers
What is the Normal Minimum Pension Age (NMPA)?
The Normal Minimum Pension Age (NMPA), is the earliest age at which most people can access their pension benefits without incurring an unauthorised payments tax charge. Following government legislation, the NMPA is increasing from 55 to 57 on 6 April 2028.
This change will apply to most pension savers. However, some pension benefits have a Protected Pension Age of 55, meaning those benefits can still be accessed from age 55 after the NMPA increase takes effect.
Protected Pension Age with Fidelity
If your client opened a Fidelity Pension, or applied to transfer their pension to us, before 4 November 2021, they will benefit from a Protected Pension Age of 55 for their Fidelity pension benefits. This protection applies to eligible pension benefits held within that pension, including future contributions made to it.
Protection is attached to the pension benefits, rather than the client personally. Where protected and non-protected benefits need to be kept separate, they may be held in separate pension accounts with different retirement age labels.
Supporting clients who want to access their pension at 55
Ahead of the Normal Minimum Pension Age increasing from 55 to 57 on 6 April 2028, we’re introducing automatic ringfencing for new cash transfers where protected pension benefits are confirmed by the transferring provider. This will help ensure protected benefits continue to be administered correctly, while keeping the process as simple as possible for you and your clients.
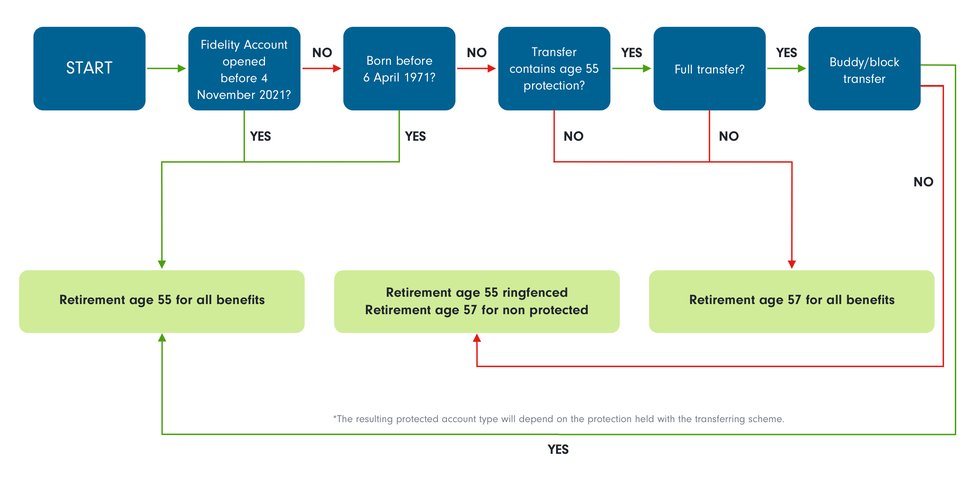
Birth dates that affect the action taken on client accounts
What will happen to my clients transfers?
From October 2026, where a new cash transfer includes protected pension benefits and the transferring provider confirms that protection, we’ll automatically ringfence those benefits on receipt. No action is required from you for the ringfencing process.
Where required, we’ll create two separate pension accounts for the client:
Minimum Retirement Age 55
For protected benefits
Minimum Retirement Age 57
For non-protected benefits
Understanding pension transfer outcomes
This applies to cash transfers only. Re-Registration transfers and transfers for immediate drawdown are not included at this stage.
What clients and advisers will see
- Clear retirement age labels of 55 or 57 on relevant pension accounts.
- In some cases, two pension accounts instead of one.
- The client’s overall pension value will remain unchanged.
- No additional charges will apply because of ringfencing.
- All future contributions and lump sums will continue to be paid into the NMPA 57 account, unless otherwise confirmed.
Transfer Scenarios
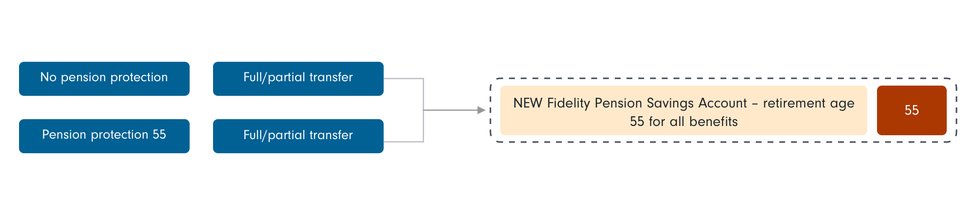
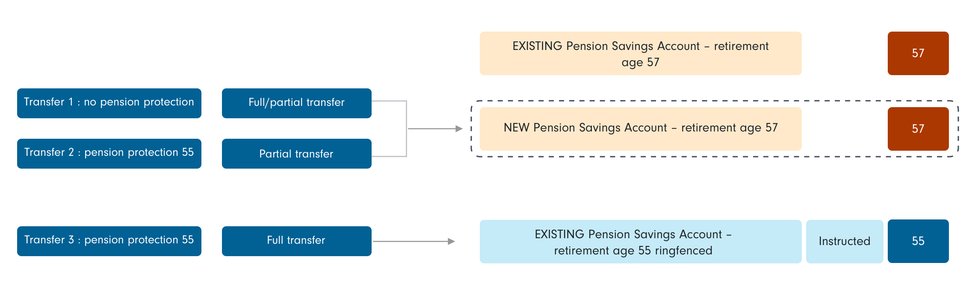
The client is generally unaffected by the NMPA increase. A new Fidelity pension savings account can be set up with benefits accessible from age 55.
Benefits without age 55 protection will be held in an account labelled Minimum Retirement Age 57.
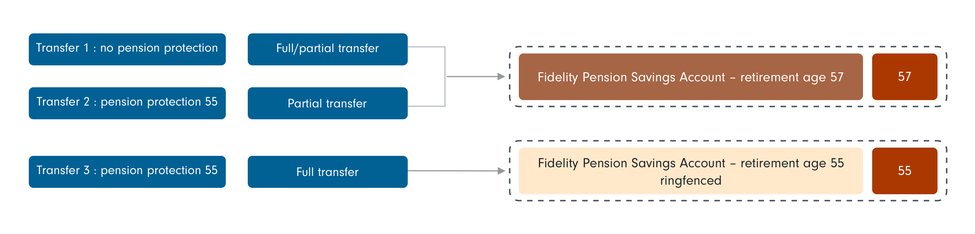
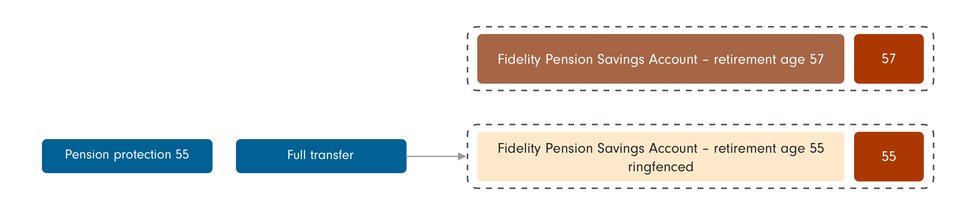
Where a full cash transfer has confirmed age 55 protection, protected benefits will be held in a separate Minimum Retirement Age 55 account, while non-protected benefits will be held in a Minimum Retirement Age 57 account.
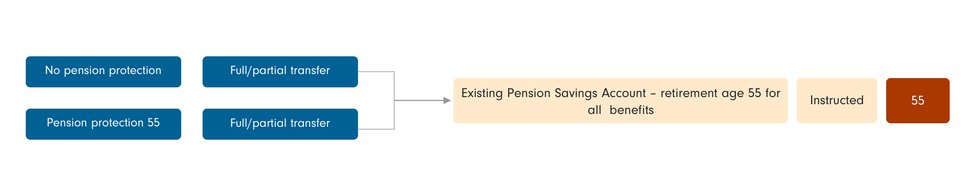
Where a transfer is instructed into an existing account where the retirement age is always 55, protected and unprotected assets can move into that account.
Unprotected and partial transfers will usually go into the existing age 57 account. Full transfers with confirmed age 55 protection may be placed into a new age 55 transfer account.
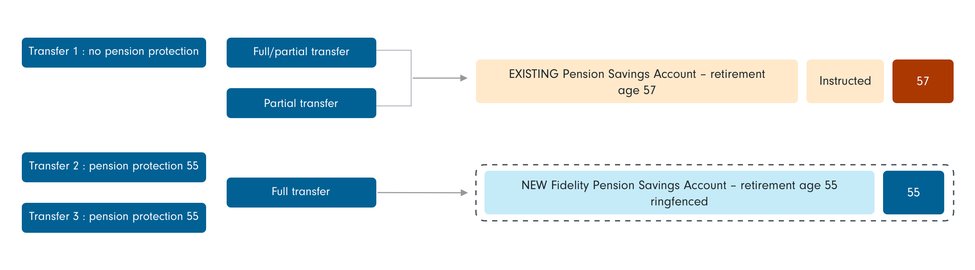
Please ensure any additional transfers are submitted to the correct account based on the applicable retirement age. If a transfer is submitted to an account with a different retirement age, we may need to create an additional account with the same settings as the original instruction, including model portfolios, fees and income treatment.
Transfer Instructed into the 57 account
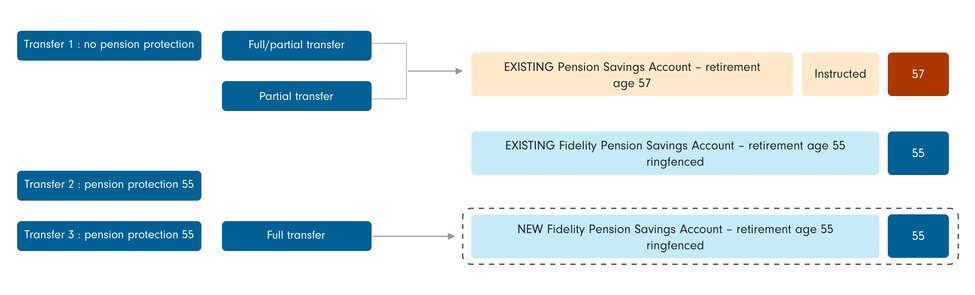
Transfer Instructed into the 55 account
Important points to note
- Ringfencing will only take place where the transferring provider confirms that the cash transfer includes protected pension benefits.
- An adviser instruction alone is not sufficient to confirm Protected Pension Age.
- If protection is not confirmed by the transferring provider, benefits will be treated as NMPA 57 unless and until the relevant protection information is received and actioned.
- This process is being introduced for new cash transfers from October 2026.
- A review of certain transfers made between 4 November 2021 and October 2026 will follow, and we’ll contact advisers before any action is taken.
What you need to do
Please take care to select the correct account when submitting a pension transfer instruction, as this will help ensure the client’s account structure is set up as intended after the transfer.
You don’t need to take any action for the automatic ringfencing process. We’ll apply the relevant retirement age labels and create separate accounts where required. If we need any further information, or if an account is affected by a future review, we’ll contact you before any action is taken on your clients accounts.
FAQ’s
Yes. Transfers between age 55 accounts are allowed, and transfers between age 57 accounts are allowed. Transfers between age 55 and 57 accounts are not allowed the separation matters due to regulatory requirements to be able to identify protected and unprotected benefits.
Not all pension benefits will have the same minimum retirement age. Ring-fencing creates clear guardrails, so protected and unprotected benefits are accessed at the correct time.
Confirmation must come from the ceding provider. If the protection information arrives late then the transfer may initially sit in the age 57 account until it can be reviewed and corrected once confirmation is available.
Yes. To retain protected pension age, the transfer must be full rather than partial.
If protected benefits are submitted against an age 57 account, Fidelity must create a separate age 55 account that mirrors the submitted model, fee and other account instructions. If you already have an appropriate transfer age 55 account and want to avoid another one, the protected transfer should be submitted to that account.
The account retirement age will be visible on the client account. New contributions will go to the NMPA57 account where applicable.
If protected funds have been consolidated into one account before the review, the calculation may create one related account. However, this may conflict with your original investment strategy and could create additional administration.
The new account is expected to mirror the original account’s model, fees, DFM fees and income treatment.
No. If a client has protection, Fidelity must preserve it; there is not currently an opt-out route.
Existing drawdown funds can continue to be accessed. However, any income dependent on new regular crystallisation or PCLS-funded phased crystallisation may need to stop until age 57. Advisers will need to identify and proactively manage affected clients.
These changes stem from complex regulatory requirements linked to the increase in the Normal Minimum Pension Age (NMPA) in 2028. Pension providers across the industry are implementing these changes and, while the required regulatory outcome is the same, there is no single industry-standard model for how they should be delivered.
Different providers are therefore adopting different operational approaches based on their own systems, products and customer needs. Regardless of the operational approach taken, all providers must ensure that benefits with different minimum retirement ages are clearly identified and managed appropriately. The key objective is to protect customers' entitlements and ensure the correct retirement age is applied to the relevant benefits.
Fidelity's approach has been designed to support the accurate administration of protected and non-protected benefits and to help deliver the changes as smoothly as possible for our customers and advisers. This has required us to take a different approach operationally in how we deliver the changes for our Personal Investing and advised clients (who will see the benefits as separate accounts) and our Workplace Investing members (who will see the benefits as separate ‘pots’ within the same/original account).